
Scottish economic insights: September 2026
Provides a summary of latest key economic statistics, forecasts and analysis on the Scottish economy.
Box 3: Consumer Sentiment across Demographic Groups
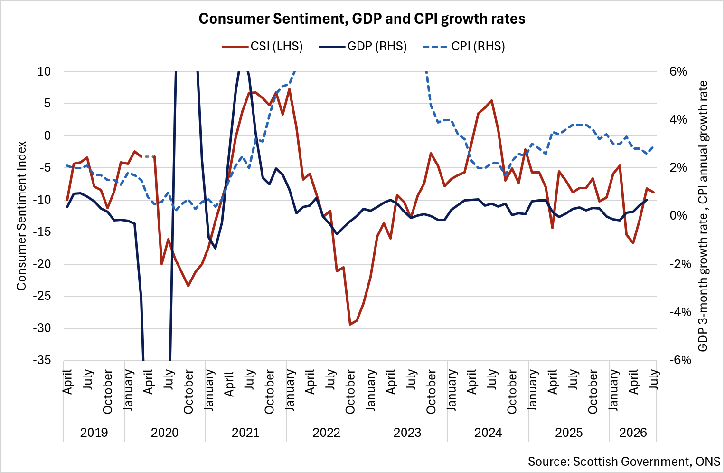
The Scottish Consumer Sentiment Indicator (SCSI) is a leading indicator of economic activity in Scotland, providing timely insight on households’ sentiment and expectations regarding the Scottish economy, their household financial security and their confidence to spend. It has provided insights into recent economic shocks, such as the Covid-19 pandemic and the cost of living crisis.
Consumer sentiment reached its lowest recorded level[35] in October 2022, when the composite Consumer Sentiment Index (CSI) fell to -29.4. While sentiment has improved since then, it remains below the series average and firmly in negative territory. This is especially prominent with regards to households’ attitudes to spending and their financial conditions. Although inflation remains lower than the levels seen in 2022 and 2023, price levels are now substantially higher than five years ago, and the recent oil price shock from the Middle East crisis is pushing up prices and weighing on household budgets.
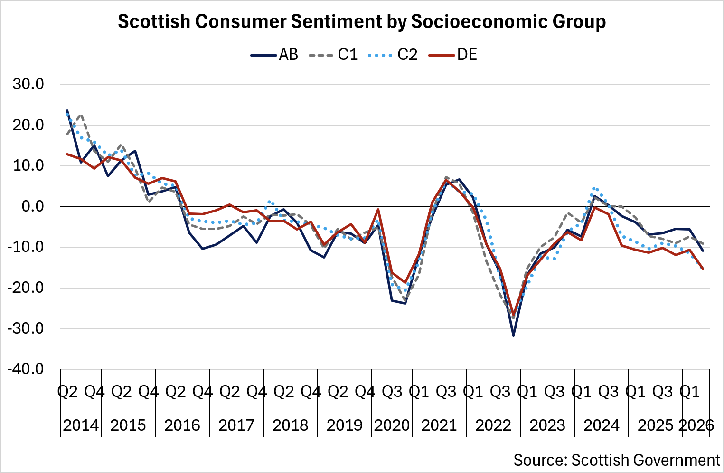
The analysis below disaggregates the SCSI across different socio-economic groups, and shows that while sentiment remains negative across all groups there are notable differences between them.
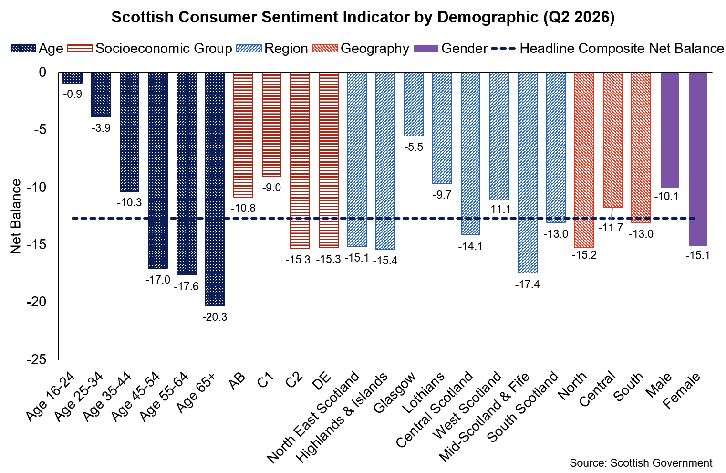
Consumer sentiment has consistently been more negative among older age groups and less negative among young adults over the course of the survey series, with the latest data for Q2 continuing to show this pattern. Much of this difference is driven by the expected financial conditions indicator, with younger adults generally reporting more optimistic expectations for their finances in the next 12 months. The composite CSI for young adults has generally been positive throughout the timeseries. However, in the latest quarter, the indicator for 16-24 year olds fell by 3 points to -0.9, falling into negative territory for the first time since Q2 2023. This compares with a reading of -20.3 among those aged 65 and over.
Differences are also evident by gender, with Q2 2026 results showing that respondents identifying as female recorded a CSI of -15.1, compared with -10.1 among those identifying as male, indicating that women, on average, continue to report more negative sentiment of the economy and their financial conditions than men. Geographic differences also exist in CSI, with respondents living near the major cities in Glasgow and the Lothians reporting less negative sentiment than those living elsewhere in Scotland, suggesting that local economic conditions have an influence on perceptions of the economy.
Notably, socioeconomic status is another important factor associated with variations in consumer sentiment. Individuals in higher socioeconomic groups (SEGs) report less negative sentiment overall than those in lower SEGs. In Q2 2026, respondents in the AB and C1 groups recorded composite CSI scores of -10.8 and -9.0 respectively, compared with -15.3 among both the C2 and DE groups. Furthermore, the gap in sentiment between higher and lower socioeconomic groups has widened in recent years, suggesting that economic pressures have been felt unevenly across households.
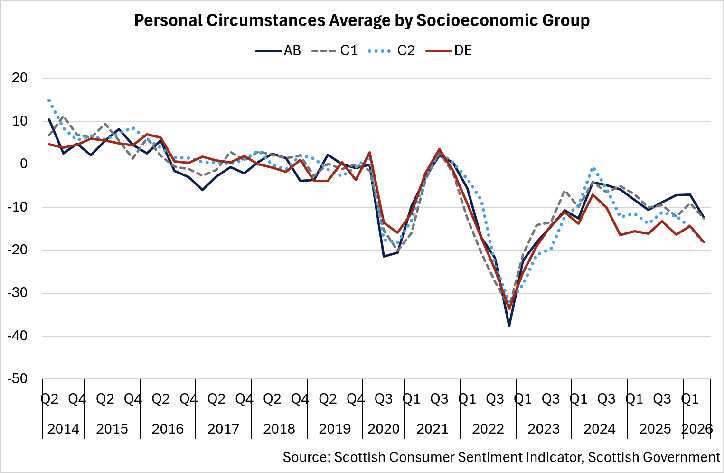
These differences are particularly evident when examining the Personal Circumstances Average, which captures respondents’ attitudes to spending alongside their assessment of current and expected household financial conditions. Since Q2 2021, the Personal Circumstances Average has remained below the composite CSI, highlighting the sustained challenges facing household budgets.
The gap between the CSI of higher and lower socioeconomic groups is particularly pronounced on the Personal Circumstances Average. In Q2 2026, this measure stood at -12.4 and -12.6 among AB and C1 respondents respectively. This compares with much lower scores of -18.4 among C2 respondents and -18.2 among those in the DE group. These finding suggest that lower-income households continue to face greater financial pressures and remain more cautious about spending than their higher-income counterparts.
In summary, consumer sentiment has fallen among all SEGs but notably more among the lower SEGs. This may be indicating legacy impacts from the inflation shock of 2022-2023, with the more recent price shock from the Middle East crisis further driving that wedge.
End of Box 3
Contact
Email: economic.statistics@gov.scot