
Scottish economic insights: September 2026
Provides a summary of latest key economic statistics, forecasts and analysis on the Scottish economy.
Box 1: How has Scotland’s trade in goods been affected by EU Exit over 2021–25?
It has now been ten years since the 2016 EU Exit referendum. On 1 January 2021, the transition period ended and the Trade and Cooperation Agreement (TCA) between the UK and EU came into force. It broadly guaranteed tariff-free trade subject to non-tariff barriers. These barriers, including rules of origin requirements, sanitary and phytosanitary barriers, more onerous administrative procedures, and border controls – all the result of the UK leaving the Single Market and Customs Union – have increased the cost of trading with the EU and caused some exporters to stop trading with the EU altogether.
These added costs and trade barriers are reflected in the trade data, with UK goods exports to the EU in 2025 being 14% lower and imports 2% lower in real terms than 2019. UK services exports recovered much faster post-Covid, while growth in UK–EU services imports have dampened (Figure 1).[9]
Figure 1. Changes in inflation-adjusted UK trade with the EU and ROW
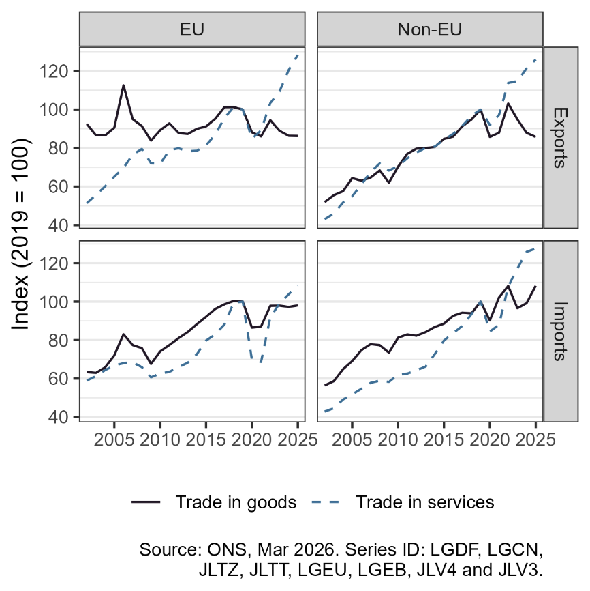
EU Exit’s impacts on UK–EU trade are clear-cut in theory. They are harder to estimate in practice, particularly due to the volatility of global trading patterns in 2022–25 (alongside the Covid-19 pandemic’s impacts on international trade prior to that), and the lack of an observable counterfactual.
Estimating the impact of EU Exit on Scottish trade flows
This analysis updates previous Scottish Government analysis[10] which utilised a synthetic control method to estimate a counterfactual in order to attempt to isolate and estimate the impacts of EU Exit on Scottish trade flows in 2021. It estimated a 12% reduction in trade in goods, with the effect primarily driven by lower imports of goods from the EU. We repeat this analysis with new 2022–25 data and improve on the methodology.[11]
Our estimates using aggregate trade data from the entire 2021–25 period were not statistically significant. The 2022–25 period was particularly volatile globally, and so it is not surprising that the inherently more volatile nature of Scottish trade data flows compared to UK trade flows during the 2021–25 period led to this result.
Breaking impacts down by quarter shows statistically significant negative impacts for Scotland–EU imports in 2021, equivalent to a reduction in goods imports between £1.1 billion (c.a. -10%) and £4.0 billion (c.a. -35%) in cash terms. Impacts on exports were largely not statistically significant, similarly to the original analysis of 2021 trade flows.
Figure 2. Estimated percentage impacts on Scottish agrifood trade flows to/from the EU27
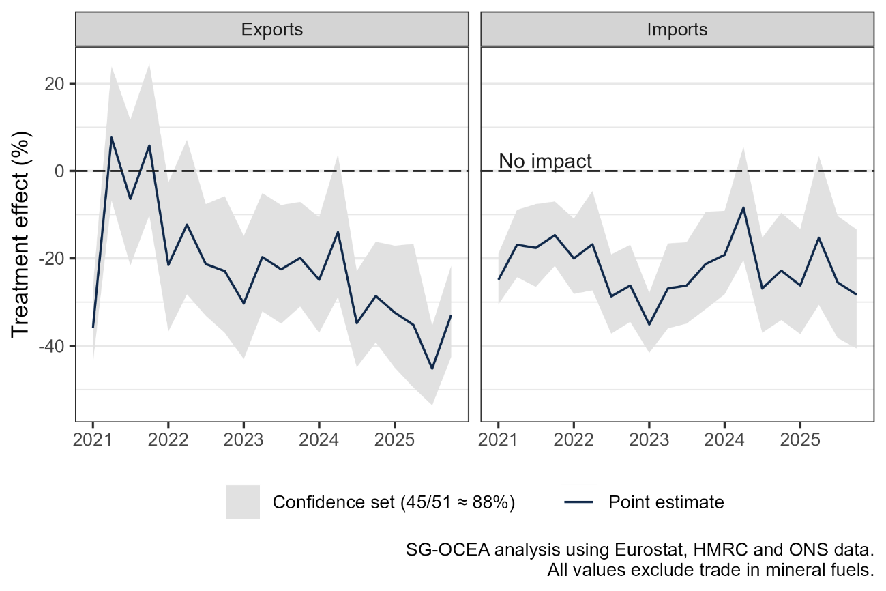
We also run the same analysis on trade data for each sector over the same 2021–25 period. This finds statistically significant results and shows that agrifood[12] is significantly impacted. On average, the quarterly value of Scotland–EU agrifood imports decreased between 14% to 30%, and agrifood exports decreased between 19% to 28%, suggesting that Scotland may have lost out on up to £2.9bn in agrifood imports from the EU, and £2.8bn in agrifood exports to the EU, over 2021–25 (Figure 2).
Comparisons with other evidence
Studies published in the lead-up and shortly following EU Exit relied on structural economic models well-suited for analysing the long-term impacts of policy changes. Results from these models are still useful today, including in helping inform the Office for Budget Responsibility’s budget forecasts.[13] For example, NIESR project that by 2035, UK–EU trade will be 25% lower (and total UK trade 15% lower) than the baseline, translating to a 5.7% reduction in UK GDP.[14]
More recently, in 2026, Springford and Spisak utilised a structural gravity model to estimate impacts of EU Exit on UK trade. They found that EU Exit resulted in substantially lower UK–EU trade, in both goods and services, and that leaving the single market had done more damage than leaving the customs union. Goods exports and imports to and from the EU were estimated to be 16% and 14% lower respectively, with exports of agrifood (-29%) and imports of machinery (-26%) and chemicals and pharmaceuticals (-24%) standing out as goods sectors with the largest impacts.[15]
A number of studies use observational data before and after EU Exit and attempt to isolate impacts of EU Exit from other factors influencing GDP or trade flows. Some studies use the EU Exit referendum as the ‘point of intervention’, and they generally find anticipatory effects of EU exit – for example, in the form of reduced business confidence and foreign direct investment.[16] Other studies use 2021 as the point of intervention, some examples of which are highlighted below.
Ayele et al (2021) estimated that EU Exit reduced UK exports to the EU by 15% and imports by 32% in 2021Q1. Particularly high impacts were seen in UK–EU exports of agrifood, automotive goods, and textiles, and in nearly all UK–EU imports.[17] Similarly, Kren and Lawless (2024) found declines in exports of 16%, and imports of 20% in 2021. They find a substantial reduction in the variety of products exported to the EU, and a lesser reduction in variety for imports.[18]
Freeman et al (2025) find that EU Exit led to an immediate and statistically significant decline in trade with the EU (relative to UK–ROW trade) in both directions. They also find that impacts were concentrated in smaller firms, with many stopping trading altogether.[19]
Du, Shepotylo and Shi (in a June 2026 draft paper) analysed monthly UK trade data from 2017 to 2025 and found that EU Exit led to a 16.5% decline in UK–EU export value and a 23.1% decrease in import value. Additionally they found that by 2025, export varieties to the EU had fallen by 53.8%, and import varieties by 31.5%.
The evidence suggests that EU Exit has dampened trade and has been particularly disruptive for small UK and Scottish businesses, many of which have stopped trading with the EU.[20] Exports have declined in their product variety, highlighting potentially large impacts on small UK exporters. UK–EU imports, which supply Scottish manufacturers, retailers and consumers, have similarly suffered in value.
It also suggests that the decline in openness and increased uncertainty has impacted on investment, employment, and productivity growth, leading to lower GDP. While some of the UK’s closest peers have faced similarly slow recoveries post-Covid, others have fared better – including the EU27. OECD data shows that GDP per capita[21] in the EU27 has grown faster than that of the UK since Covid-19, with GDP per capita now 1% higher in the EU27 than the UK (compared to 9% below in 2019).
Agrifood, one of the sectors subject to large increases in non-tariff barriers, emerges as a particularly heavily impacted sector. This is echoed by our analysis of Scottish trade flows. We continue to monitor Scottish trade flows and estimate impacts of large trade policy changes on Scotland’s economy where appropriate.
Contact
Email: economic.statistics@gov.scot