
Scottish economic insights: September 2026
Provides a summary of latest key economic statistics, forecasts and analysis on the Scottish economy.
Economic outlook
Latest forecasts
The near term global economic outlook continues to be heavily influenced by the ongoing conflict and uncertainty in the Middle East. The recent escalations in military action have caused another increase in global oil prices. Together with the ongoing rises in UK wholesale gas prices, these put pressure on inflation and weigh on the outlook. In July, the IMF forecast global economic growth to slow from 3.5% in 2025 to 3.0% in 2026, before recovering to 3.4% in 2027, and for global inflation to rise form 4.1% in 2025 to 4.7% in 2026, before easing to 3.9% in 2027. However, the latest escalation presents a downside risk to these forecasts, which expected a normalisation of supply through the Strait of Hormuz, which is yet to materialise.[36]
At a UK level, the latest HMT average of independent forecasts from August shows that GDP growth is expected to average 1.1% over 2026 and 1.3% over 2027. The forecast for 2027 reflects a downgrade from the forecast in February, prior to the Middle East conflict, when GDP was expected to rise by 1.4% 2027 respectively (and 1.1% over 2026).[37]
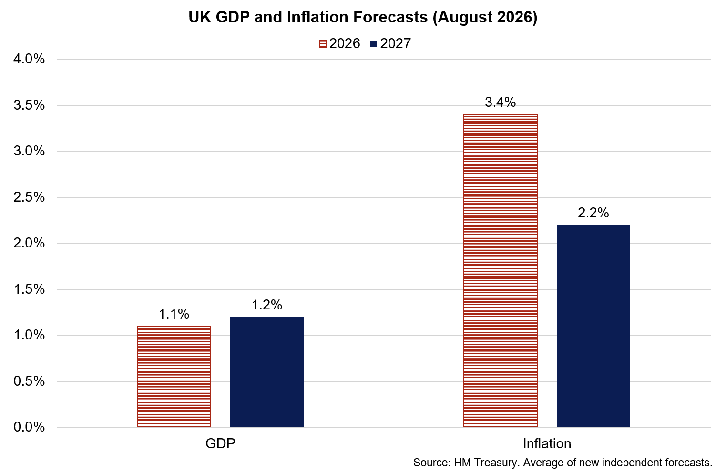
The UK inflation outlook is highly uncertain, influenced by how long the conflict continues and how supply and prices of oil and gas recover. The HMT average of independent forecasts from August projects inflation to average 3.4% in the final quarter of 2026 and ease to 2.2% in 2027. This reflects an upgrade from forecasts in February when inflation was expected to average 2.2% across both years. In July, the Bank of England presented three scenarios for the UK inflation outlook, dependent on how energy prices evolve and how they feed into second round inflationary impacts. Each scenario sees inflation increasing in the second half of 2026. The central and mild scenarios both see inflation peak in fourth quarter of the year, with the central scenario projecting it to peak at 3.2%, while the mild scenario projects it peak at 3.0%. Inflation is then projected to return to the 2% target around the end of 2027. However, in the adverse scenario, inflation is projected to rise to 3.8% in the fourth quarter and then further to its peak at 4.5% in the second quarter of 2027. In this scenario inflation is projected to remain above target throughout the forecast period.[38]
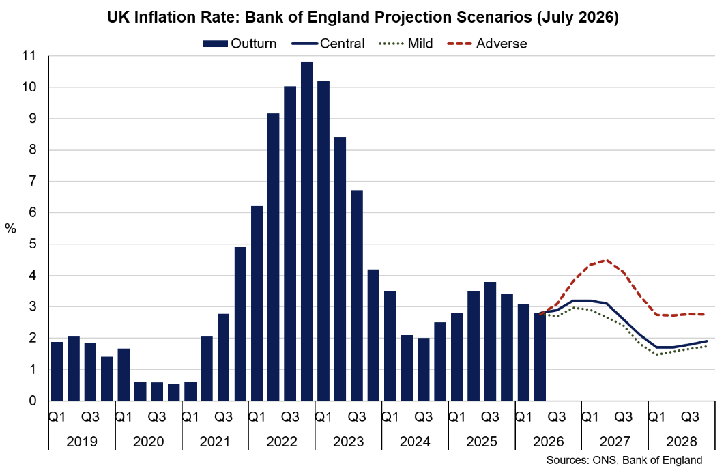
As of now, there is little evidence that the rise in energy prices has fed through to second round impacts, however the transmission of the price rises is still progressing through and recent escalations risk energy prices remaining elevated for longer than expected. As Europe approaches winter the pressures on wholesale gas prices are rapidly increasing. As highlighted by the recent decision of the European Central Bank to increase interest rates, inflationary risks are increasing and the outlook for businesses and consumers alike is increasingly challenging.
Contact
Email: economic.statistics@gov.scot