
Scottish economic insights: September 2026
Provides a summary of latest key economic statistics, forecasts and analysis on the Scottish economy.
Household conditions
Inflation
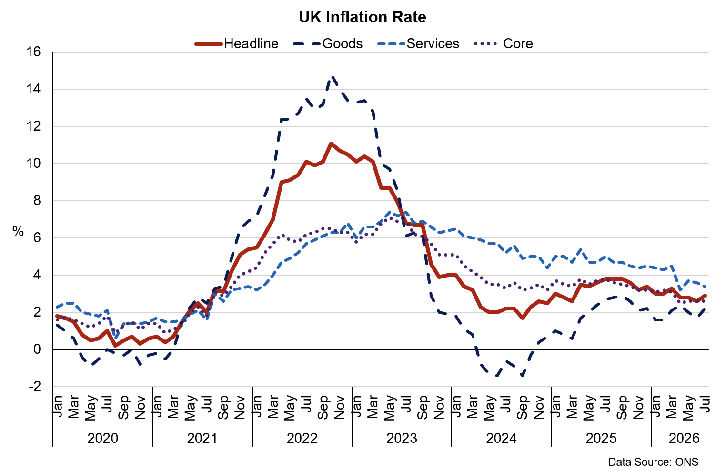
Over the last six months, UK inflation has been lower than at the start of the year, but above what was forecast prior to the energy price shock caused by the Middle East conflict. Latest data shows that inflation picked up to 2.9% in July, up from 2.6% in June, reflecting the 12.6% increase in the Energy Price Cap.[25]
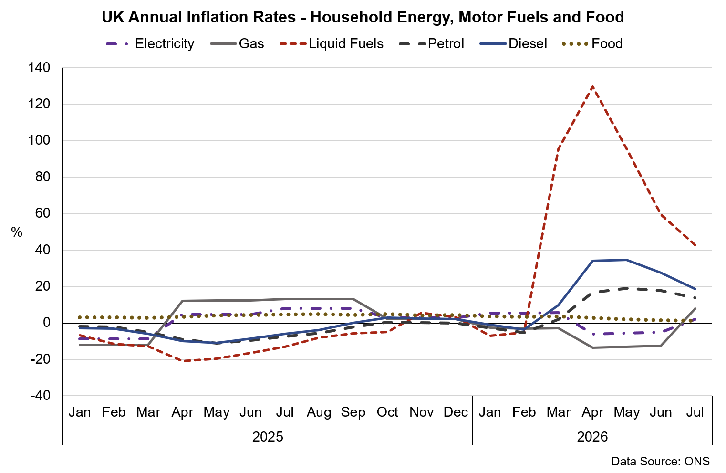
In addition to household gas and electricity prices increasing (8.0% and 2.1%, respectively), road fuel prices inflation added upward pressure to the headline inflation rate. In July, diesel prices rose by 18.5% and petrol prices rose by 13.7%, both easing from their rates in June but still notably above the rates recorded prior to the conflict. Road fuel prices have continued to rise, and petrol prices are now at their highest level since November 2022. Liquid fuel inflation also remains elevated (42.8%), albeit eased to its slowest rate since February.
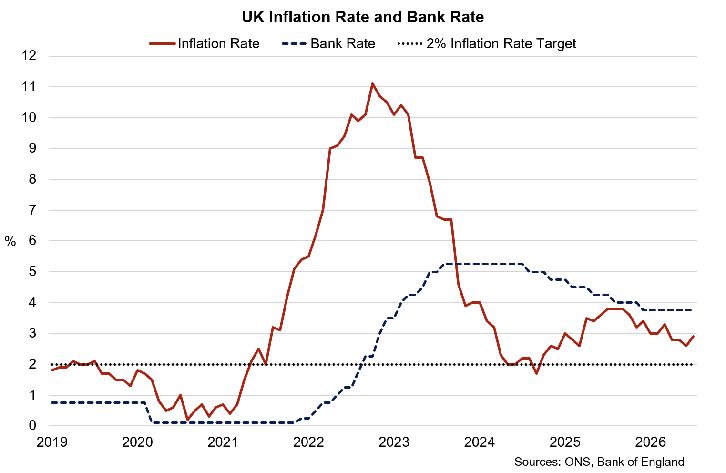
Inflation is expected to increase in the coming months, with the Bank of England projecting inflation to peak at 3.2% in Q4. The Bank’s Monetary Policy Committee held the Bank Rate unchanged for the fifth consecutive time in July at 3.75%. The Bank’s next rate decision is set for the 17th September, with investors expecting the Bank to hold rates unchanged again. [26],[27]
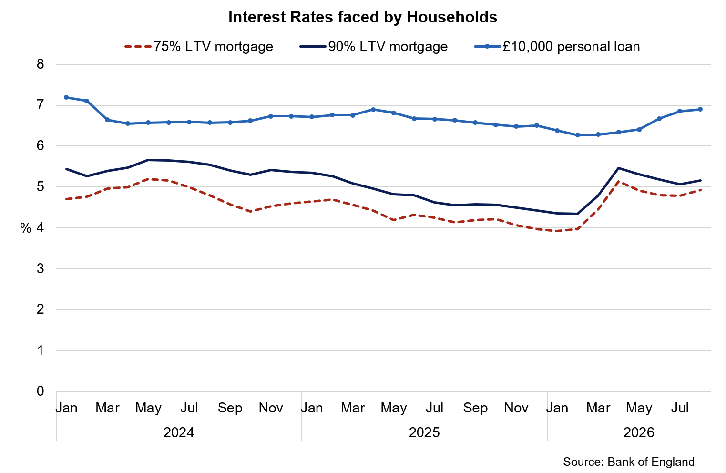
Nonetheless, increased expectations of inflationary pressures and potentially tighter monetary conditions have fed into higher borrowing costs for households. For example, interest rates on two-year 75% and 90% loan‑to‑value (LTV) mortgages spiked following the escalation in the Middle East conflict. The rates eased over May and June but picked up again moderately in July to 4.92% and 5.16% for 75% and 90% LTV mortgages respectively. Interest rates on £10,000 personal loans have also increased, with the rate reaching 6.9% in July.[28]
Contact
Email: economic.statistics@gov.scot