
Scottish Housing Market Review: Q3 2026
Quarterly bulletin collating a range of previously published statistics on the latest trends in the Scottish housing market.
Part of
8. Mortgage Arrears and Possessions
8.1. Arrears
The number of regulated mortgage accounts entering arrears in the UK nearly doubled (up 83%) over the period from Q3 2021 to Q3 2023 as inflation and interest rates spiked. The number of mortgages entering arrears then fell by nearly a third (32%) between Q3 2023 and Q3 2025 following an easing in inflation and interest-rate trends, and since then has been relatively steady. The latest data show the number of mortgage accounts entering arrears was 10,456 in Q2 2026, slightly down (by 2.1%) from Q3 2025.
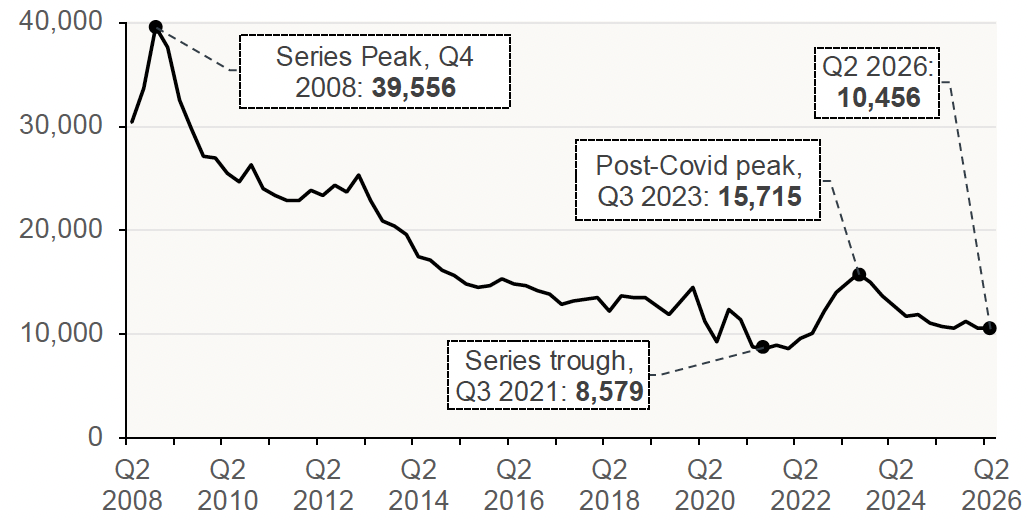
Source: FCA. Includes both securitised and unsecuritised loans.
The decrease in mortgages entering arrears since Q3 2023 has fed through to the total stock of regulated UK mortgage accounts in arrears, which has fallen by 17% from a post-pandemic peak of 148,943 in Q2 2024 to 126,913 in Q2 2026. [Source: FCA]
Similarly, Chart 8.2, which breaks down arrears by degree of severity, shows that the share of lenders' outstanding regulated mortgage balances in arrears of more than 1.5% of the outstanding loan balance has edged down from a recent peak of 1.2% to stand at 1.0% in Q2 2026. However, this remains above the post-pandemic low of 0.7% in Q3 2022.
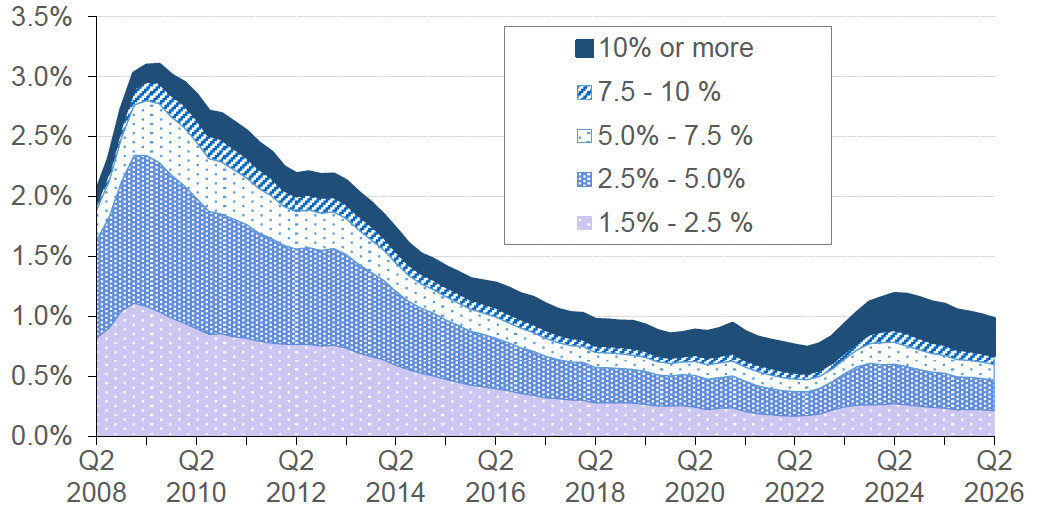
Source: FCA. Includes both securitised and unsecuritised loans; share is calculated as balances on cases which are in arrears expressed as a % of total loan balances.
UK Finance data shows that there were 11,520 buy-to-let (BTL) mortgages in arrears of 1.5% or more of the outstanding balance across the UK at the end of Q2 2026, down by 5.0% from the previous quarter. This is the tenth consecutive quarter-on-quarter fall, with the number of BTL mortgages in arrears falling by 41% since its recent peak of 19,570 in Q4 2023. BTL mortgages in arrears as share of total BTL mortgages has fallen from 0.99% to 0.60% over this period.
FCA data for non-regulated lending includes BTL lending but also some other types of lending and is collected on a somewhat different basis to the UK Finance data.[6] This data, as illustrated in Chart 8.3, shows that while the share of non-regulated mortgages which are 1.5% or more in arrears has stabilised after increasing during the cost-of-living crisis, there has been a smaller fall in recent quarters than for BTL mortgages specifically, with the share remaining unchanged from the previous quarter at 1.5% of total non-regulated residential loans in Q2 2026.
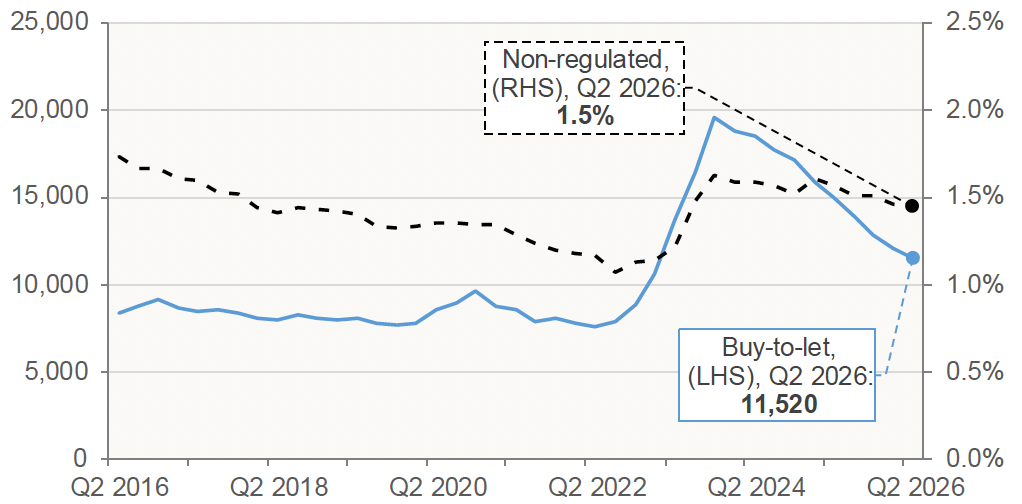
Source: Buy to Let – UK Finance; Non-regulated loans – FCA. FCA data includes both securitised and unsecuritised loans; the share of loans in arrears is the number of loans in arrears as a percentage of all non-regulated loans.
8.2. Possessions
For regulated mortgages in the UK, the continued decline in both the flow of mortgages entering arrears and the overall stock of mortgages in arrears has contributed to a reduction in mortgage possessions. In Q2 2026, there were 1,164 new possessions, a 12% decrease compared with the recent peak of 1,328 in Q3 2025, and below its pre-Covid levels (a quarterly average of 1,318 in 2019). [Source: FCA]
Meanwhile, there were 894 non-regulated mortgage possessions in the UK in Q2 2026, a decrease of 28% from the recent peak of 1,240 in Q1 2024. However, the number of non-regulated mortgage possessions was slightly above its pre-Covid levels (a quarterly average of 889 in 2019). [Source: FCA]
With respect to BTL mortgages (a component of non-regulated mortgages), UK Finance data show that there were 630 BTL mortgages in the UK taken into possession in Q2 2026, a 30% fall from the recent peak of 900 in Q3 2025, and somewhat below pre-Covid levels (the 2019 quarterly average was 668).
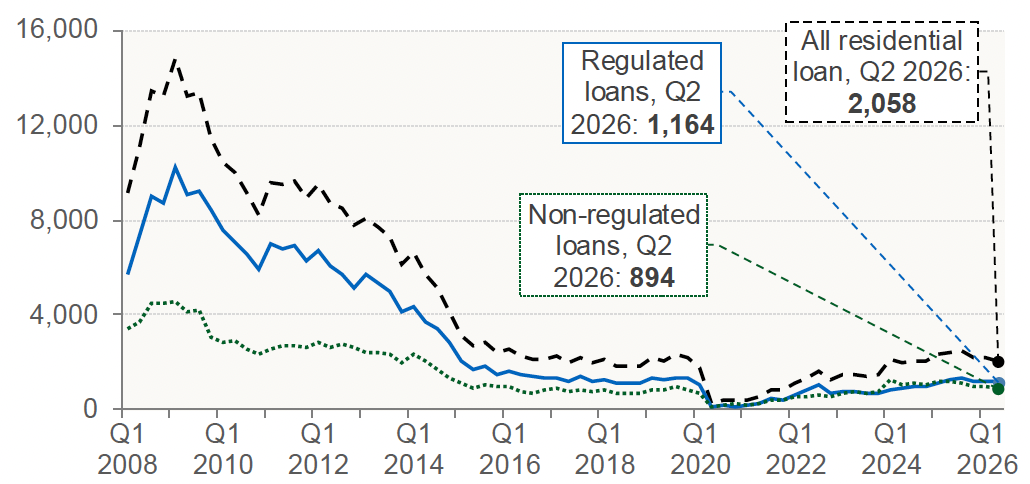
Source: FCA
Contact
Email: Orhan.McDonald@gov.scot