
Scottish Housing Market Review: Q3 2026
Quarterly bulletin collating a range of previously published statistics on the latest trends in the Scottish housing market.
Part of
3. Residential Land and Buildings Transaction Tax
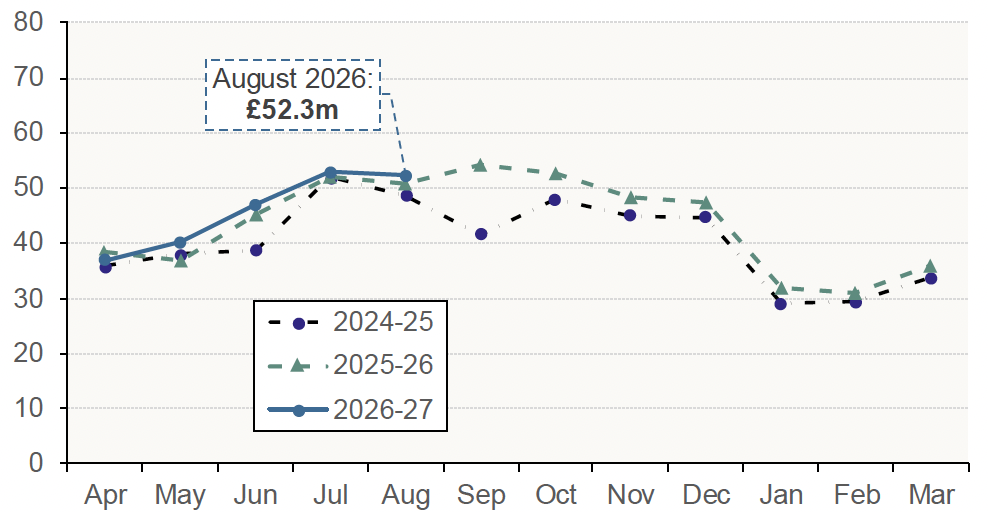
Provisional estimates indicate that Residential LBTT revenues (excluding Additional Dwelling Supplement) have been higher for most months in 2026-27 than they were in 2025-26, with the £229.5m raised between April 2026 and August 2026 representing an annual increase of 2.6% (see Chart 3.1). Within this, more recent months indicate a slight softening in the growth rate, with combined revenues across July and August 2026 up by 2.2% compared to the same months in 2025.
Please note that there was an error in the Q2 2026 Review, where the figures relating to LBTT revenues (excluding the Additional Dwelling Supplement) included both residential and non-residential LBTT, rather than only residential LBTT.
Source: Revenue Scotland
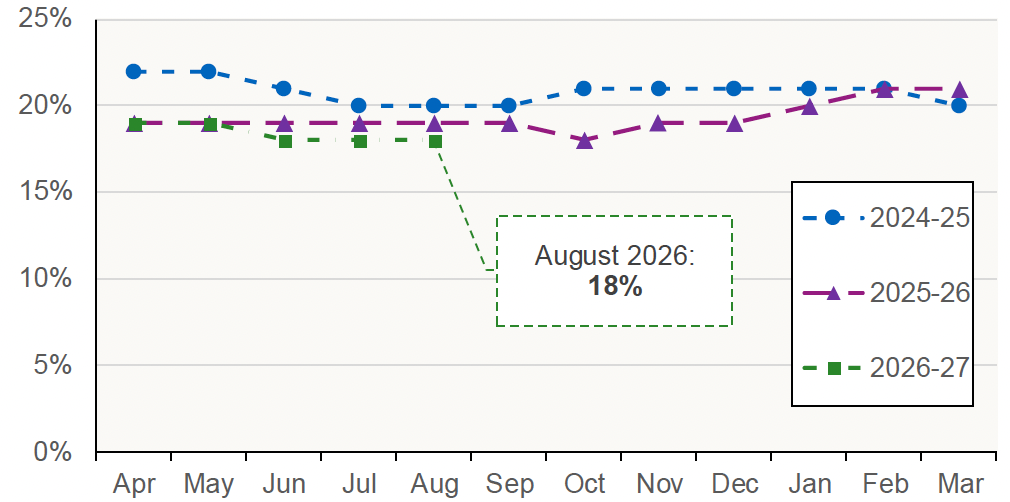
Chart 3.2 plots the percentage of total residential returns received where ADS was declared due. ADS is a flat rate tax (payable in addition to LBTT) on the purchase price of an additional residential property (e.g. a second home). It was first introduced in 2016, with the tax rate initially set at 3%, before being increased to 4% in January 2019, 6% in December 2022 and 8% in December 2024. The share of residential transactions where ADS was declared fell from an average of 23% in 2023/24 to 21% in 2024/25 and 19% in 2025/26. The most recent data show that ADS was declared due on 18% of residential transactions in August 2026.
Source: Revenue Scotland
Contact
Email: Orhan.McDonald@gov.scot