
Scottish Housing Market Review: Q3 2026
Quarterly bulletin collating a range of previously published statistics on the latest trends in the Scottish housing market.
Part of
5. Mortgage Advances, Approvals and LTVs
5.1. New Mortgage Advances
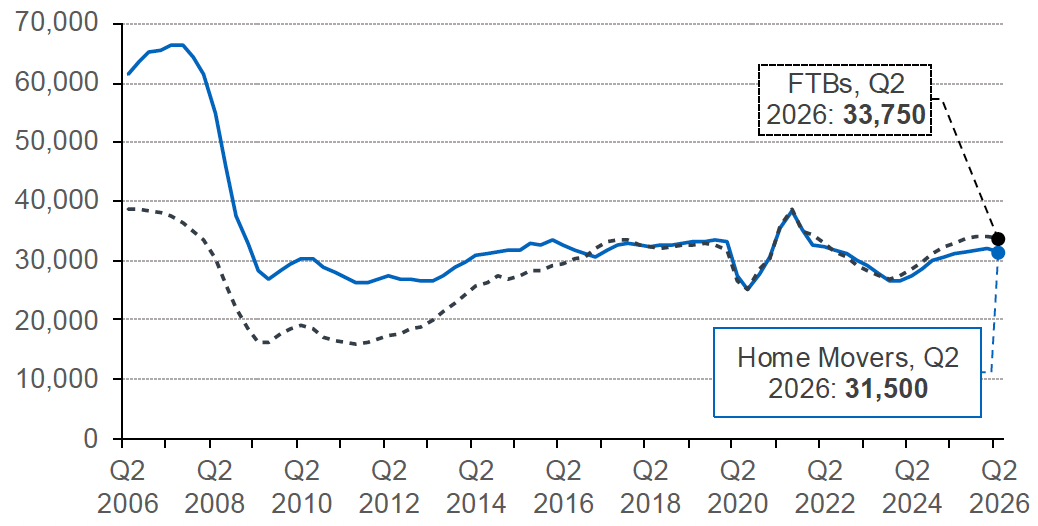
Chart 5.1 shows the trend in new mortgages advanced for home purchase, using a four-quarter moving total [Source: UK Finance]. A mortgage advance is a mortgage loan that has been paid out by the lender. In the four quarters ending Q2 2026, the number of new mortgages advanced to home movers in Scotland increased by 1.2% compared with the previous 4 quarters. However, this represented a marked slowdown in growth from 13.5% in the corresponding period ending Q2 2025.
A similar pattern was evident among first-time buyers. In the 4 quarters ending Q2 2026, the number of new mortgages advanced to first-time buyers increased by 2.7% compared with the previous 4 quarters. Again, this was significantly lower than the 15.5% annual growth recorded in the corresponding period ending Q2 2025.
This slowdown was also evident within the latest 4 quarters. The annual growth rate for new mortgages advanced to home movers fell from 4.6% in Q3 2025 to -6.2% in Q2 2026. Similarly, the annual growth rate for mortgages advanced to first-time buyers declined from 8.3% in Q3 2025 to -4.7% in Q2 2026, the second consecutive quarter where annual growth has been negative.
Source: UK Finance
5.2. Mortgage Approvals
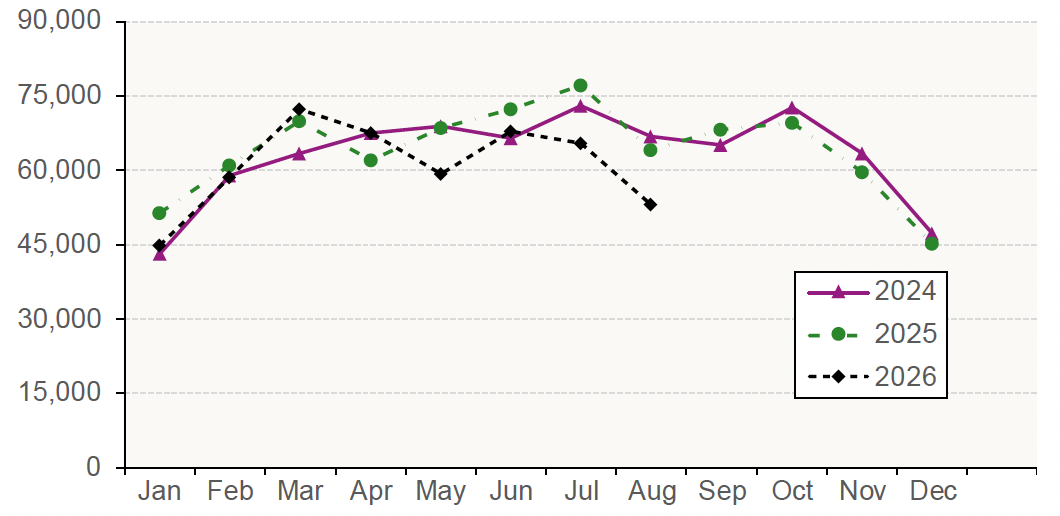
Chart 5.2 plots the monthly number of mortgage approvals across the UK for house purchase by individuals. Mortgage approvals for house purchase, which are the firm offers of lenders to advance credit fully secured on dwellings by a first-charge mortgage, are a leading indicator of mortgage sales as they reflect activity early in the buying process.
The number of mortgage approvals in the UK fell by an annual 3.8% in H1 2026. An even sharper fall is evident in the most recent months, with the number of mortgage approvals across July and August 2026 falling by an annual 15.9%. [Source: Bank of England].
Source: Bank of England
5.3. Loan-to-Value (LTV) Ratios
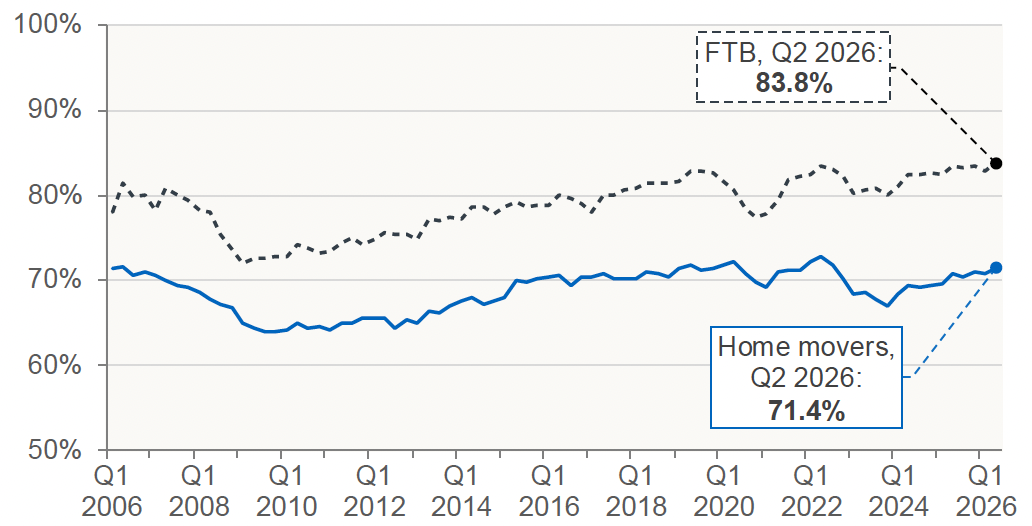
Chart 5.3 shows that the mean LTV ratio rose over the quarter for both first-time buyers and home movers. For first-time buyers, the ratio rose from 82.8% to 83.8%, while for home movers it increased from 70.7% to 71.4% in Q2 2026. The latest increase brought the quarterly average LTV ratio for first-time buyers to its highest since this series began in Q2 2005, while for home movers it was below the series peak of 72.7% in Q2 2022. [Source: UK Finance]
Source: UK Finance
In the UK, the share of regulated residential lending with an LTV ratio above 90% increased from 8.8% in Q1 2026 to 9.1% in Q2 2026. Similarly, the share of loans with both an LTV greater than 90% and a high income multiple increased from 6.7% to 6.9% over the same period. For each series, except for a similar level recorded in Q4 2025, they were at their highest level since Q2 2008, prior to the worst impacts of the financial crisis on the UK mortgage market.
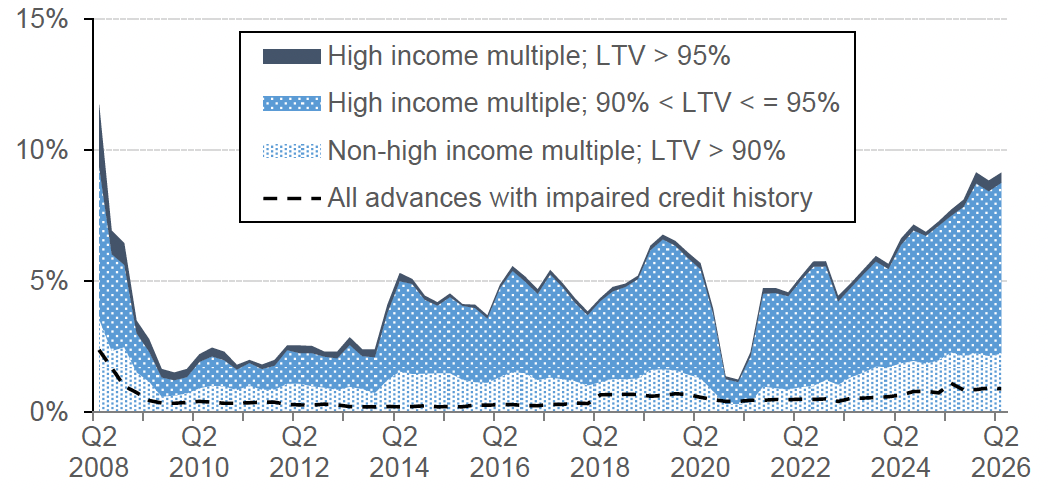
Source: FCA. Higher-risk lending is classified by the FCA as an LTV over 90% or an income multiple greater than or equal to 3.5 for single-income purchasers or 2.75 for joint-income purchasers.
The total number of residential mortgage products in the UK increased by 159 over the month to stand at 7,516 in early September 2026, which is the highest since early February 2026 (7,537), immediately prior to the escalation of the US-Iran conflict in late February. Over the month, product availability increased across all LTVs. The largest rise occurred in the 85% LTV tier, where the number of products grew by 55, reaching a total of 1,028. [Source: Moneyfacts UK Mortgage Trends Treasury Report].
Similarly, the number of buy-to-let (BTL) mortgage products, which had fallen to 4,758 in early April, increased to 5,358 in early September 2026; However, this remained 7% below the series high of products recorded in February 2026 (5,747). [Source: Moneyfacts UK Mortgage Trends Treasury Reports]
Moneyfacts note that the average shelf-life of a residential mortgage product fell from 21 days in the seven months leading up to the escalation of the conflict in February 2026 to just 13 days in the seven months since then, reflecting volatility in the mortgage market.
Contact
Email: Orhan.McDonald@gov.scot