
Shaping the Future: Strengthening Scotland's education system through empowered schools
Final report of the Independent Professional Advisor on future school reform in Scotland, with a focus on improvement, funding and governance.
Appendix C - Local Authority Funding
Scottish Government
The Scottish Government publishes a draft budget every year, usually in December, which is subject to parliamentary scrutiny and approval. The final Scottish Budget, generally agreed in February, is accompanied by the Local Government Finance settlement, which outlines the funding each council will receive.
The Scottish Government will provide £15.2 billion to local authorities in 2025/26.
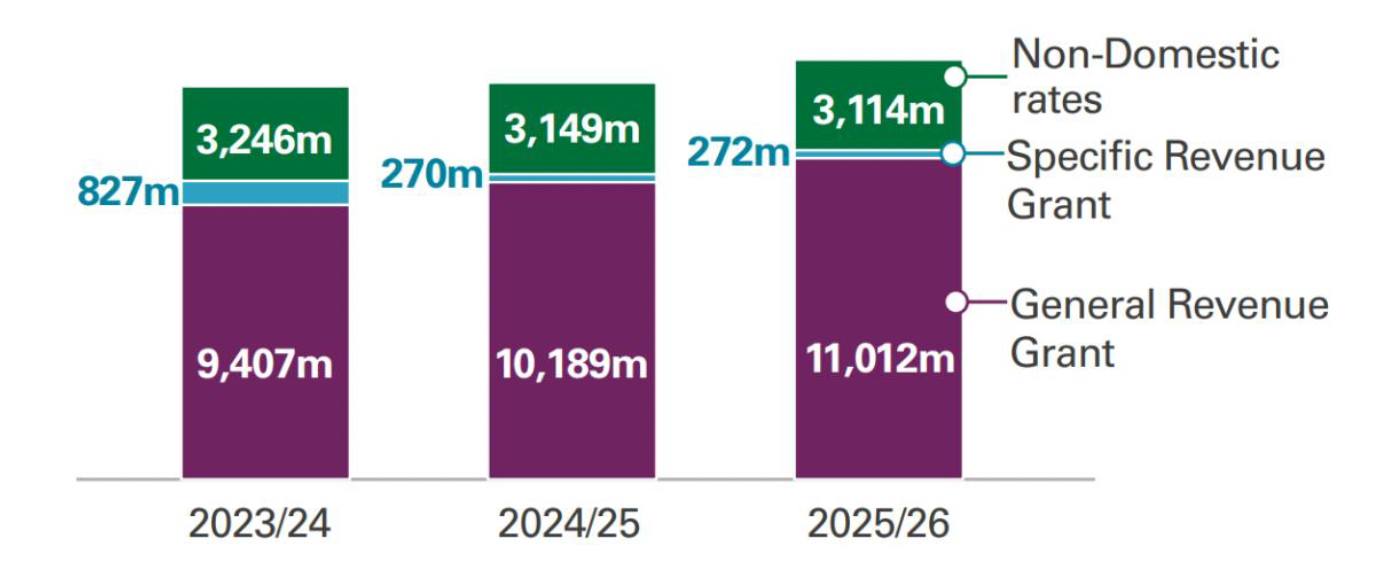
The level of funding allocated to local authorities is expected to change throughout the year as additional funding is made available to councils. This is why the 2025/26 local government budget is £15.2 billion compared to £14.3 billion above.
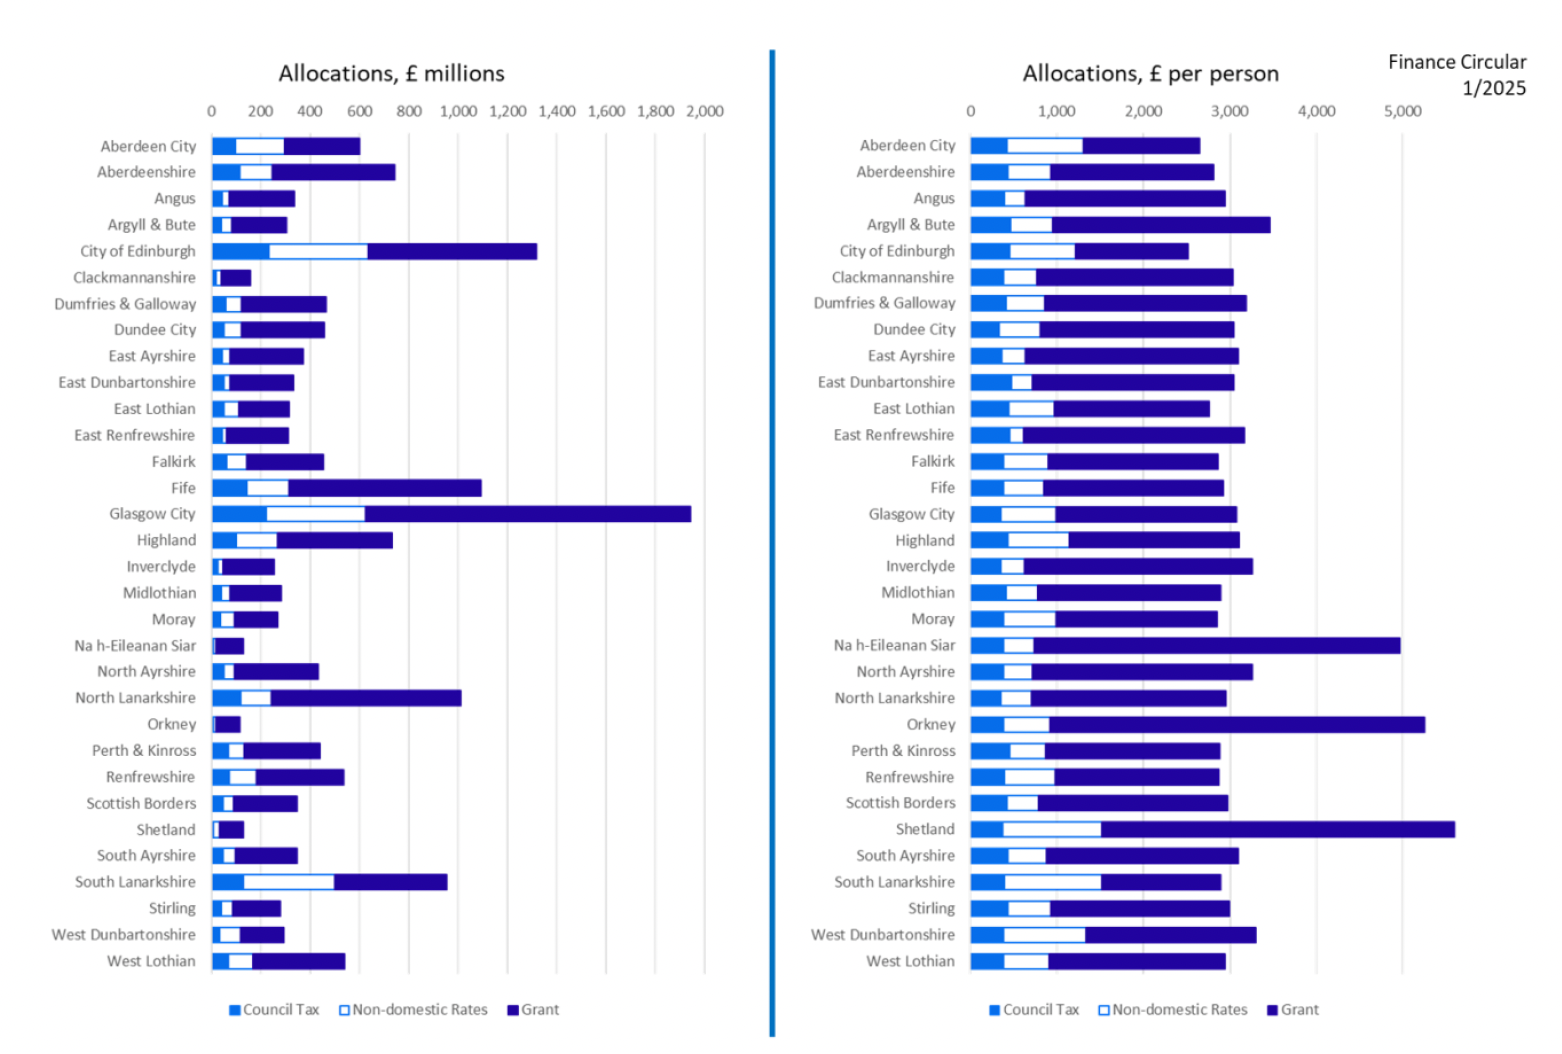
The Scottish Government seeks to distribute its funding fairly between local authorities by considering a number of criteria including population, pupil numbers, deprivation, rurality, and service indicators for other non-education statutory services. The Convention of Scottish Local Authorities (COSLA), the national association of Scottish councils, is closely involved on distribution mechanisms.
All councils are receiving an increased revenue allocation in 2025/26, in both cash and real terms.[86]
There is no specific funding for education or other policy areas set by the Scottish Government. There are, however, a few Scottish Government led initiatives for education that are ring fenced for specific purposes and outcomes such as the Scottish Attainment Challenge and Pupil Equity Fund.
The debate between the Convention of Scottish Local Authorities (COSLA) and the Scottish Government over ring-fencing centres on the balance between national policy priorities and local autonomy, with 2026 budget discussions indicating roughly 7% of revenue allocation to local government is either ring-fenced or tied to specific national policies. COSLA argues that high levels of ring-fencing and national initiatives restrict local council’s flexibility to make local decisions, making it difficult to manage rising costs and demands on services. They argue that the cumulative effect of ring-fencing and real-terms cuts is leading to the "enfeebling" of local democracy. The Scottish Government often highlights that they are now providing record funding for local government and have provided consecutive real terms increases as confirmed by external commentators such as SPICe and the Accounts Commission. This has allowed local authorities to protect critical services like education. Scottish Government would also note that in 2025-26 only 2.7% or £0.4 billion was formally ring-fenced for specific joint priorities such as the Pupil Equity fund, Gaelic and Criminal Justice Social Work. They emphasise that they are delivering a fair settlement despite challenging financial conditions from the UK government.
Local Council Budgets
Scottish Government’s policy towards local authorities’ spending is to allow local authorities the financial freedom to operate independently. It is then the responsibility of individual local authorities to manage their own budgets and to allocate the total financial resources available to them, including on education, on the basis of local needs and priorities, having first fulfilled their statutory obligations and the jointly agreed set of national and local priorities. It is for locally elected representatives to make local decisions on how best to deliver services to their local communities.
Education has the highest net revenue expenditure (NRE), with just under £8bn in 2024-25, and a budget estimate for 2025-26 of a little more than £8bn. Education accounts for nearly half of general fund net revenue expenditure in all years since 2021-22.[87]
| Local council | NRE on education (£mn) | Proportion of overall General Fund NRE | NRE per primary school pupil (£) | NRE per secondary school pupil (£) |
|---|---|---|---|---|
| Aberdeen City | 268,883 | 50% | 7,107 | 8,291 |
| Aberdeenshire | 397,989 | 54% | 7,088 | 8,663 |
| Angus | 159,923 | 49% | 7,167 | 9,023 |
| Argyll & Bute | 146,965 | 49% | 10,160 | 11,807 |
| City of Edinburgh | 582,116 | 47% | 6,686 | 8,213 |
| Clackmannanshire | 80,326 | 53% | 7,658 | 9,892 |
| Dumfries & Galloway | 208,138 | 47% | 8,081 | 9,517 |
| Dundee City | 199,134 | 46% | 6,754 | 8,280 |
| East Ayrshire | 174,481 | 52% | 7,157 | 8,614 |
| East Dunbartonshire | 191,185 | 60% | 7,446 | 9,982 |
| East Lothian | 146,014 | 49% | 6,857 | 8,435 |
| East Renfrewshire | 173,792 | 59% | 6,988 | 8,654 |
| Falkirk | 233,708 | 52% | 7,228 | 8,755 |
| Fife | 510,228 | 48% | 7,219 | 8,550 |
| Glasgow City | 821,145 | 46% | 7,019 | 9,677 |
| Highland | 366,595 | 51% | 8,065 | 9,909 |
| Inverclyde | 113,231 | 49% | 7,159 | 9,195 |
| Midlothian | 165,033 | 56% | 8,111 | 8,562 |
| Moray | 134,806 | 51% | 7,147 | 8,751 |
| Na h-Eileanan Siar | 56,987 | 49% | 13,100 | 14,358 |
| North Ayrshire | 192,554 | 47% | 7,880 | 9,621 |
| North Lanarkshire | 512,858 | 55% | 6,753 | 8,316 |
| Orkney Islands | 48,856 | 45% | 11,876 | 14,806 |
| Perth & Kinross | 212,227 | 49% | 7,946 | 10,126 |
| Renfrewshire | 260,401 | 52% | 7,522 | 8,233 |
| Scottish Borders | 162,350 | 48% | 7,762 | 9,951 |
| Shetland Islands | 58,676 | 48% | 12,241 | 14,010 |
| South Ayrshire | 153,517 | 47% | 7,771 | 8,161 |
| South Lanarkshire | 485,983 | 56% | 7,544 | 9,225 |
| Stirling | 145,561 | 52% | 8,273 | 9,802 |
| West Dunbartonshire | 137,104 | 51% | 8,354 | 8,966 |
| West Lothian | 277,230 | 56% | 7,533 | 8,070 |
| Scotland | 7,777,996 | 50% | 7,412 | 9,033 |
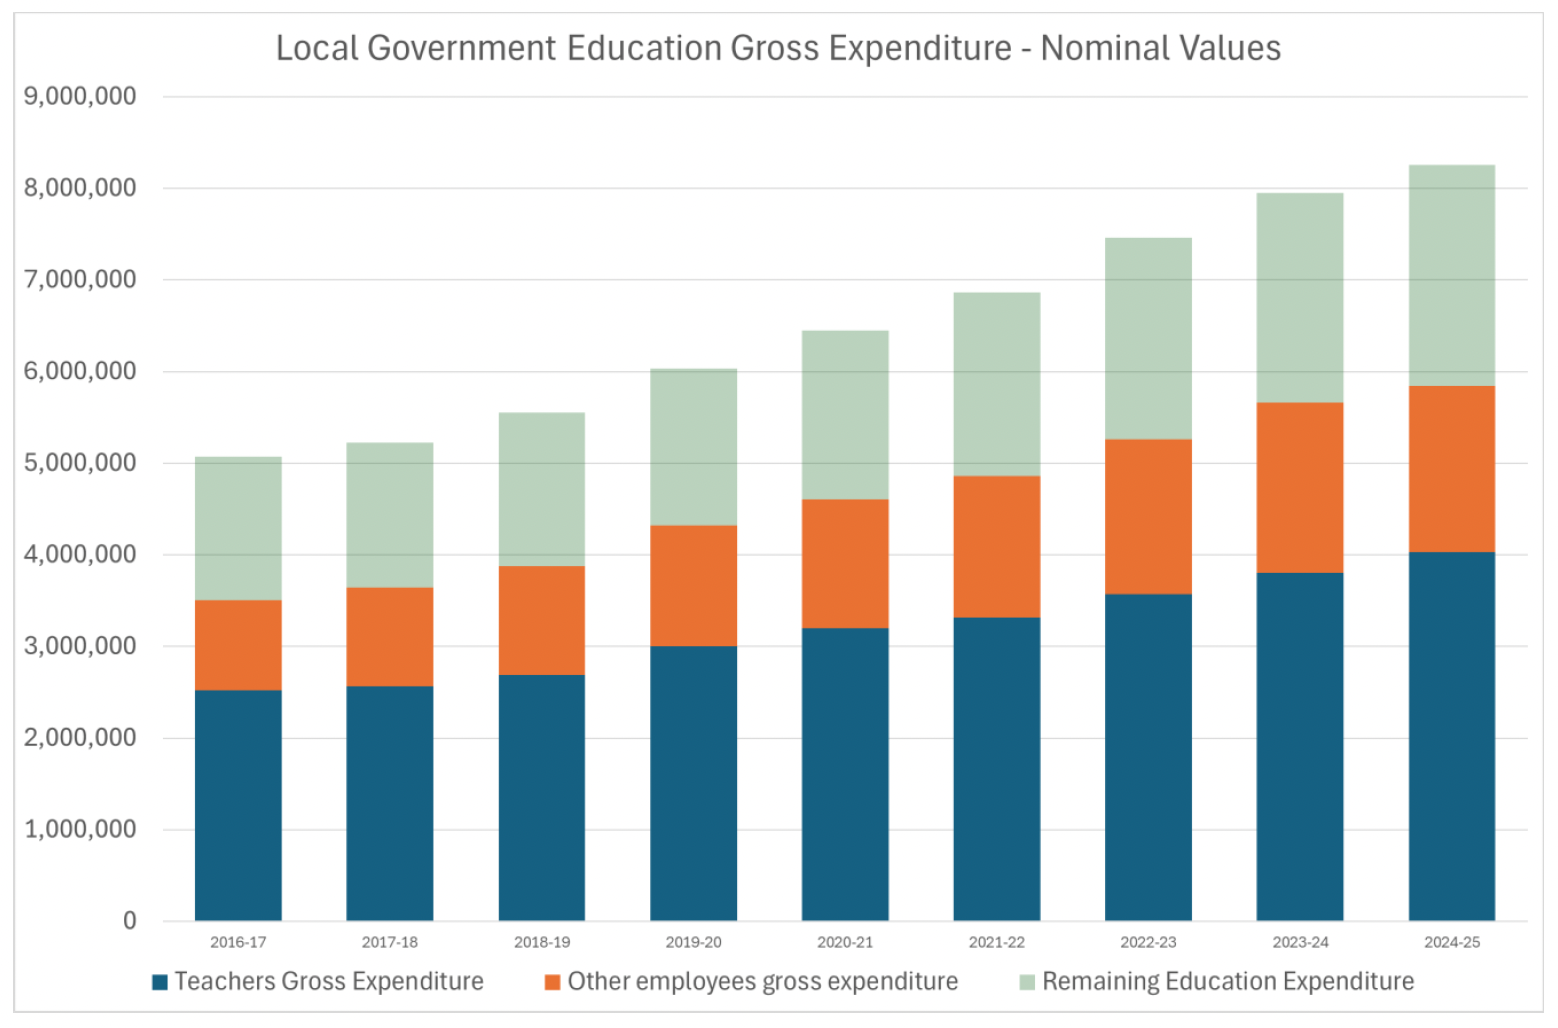
Over the past decade, overall spending on education has continued to grow. Recent increases in education expenditure are mainly driven by the teachers’ pay award and additional funding from Scottish Government for policies such as increase in early learning and childcare, the Scottish Attainment Challenge, and expansion of free school meals. Taking inflation into account, council revenue spending on school education across Scotland increased by 16% between 2010/11 and 2024/2025, from £5.8 billion to £6.7 billion. In 2024/25 councils spent £1 billion on early years, £2.8 billion on primary education and £2.8 billion on secondary education, an increase of 141%, 9%, and 2% respectively since 2010/11.
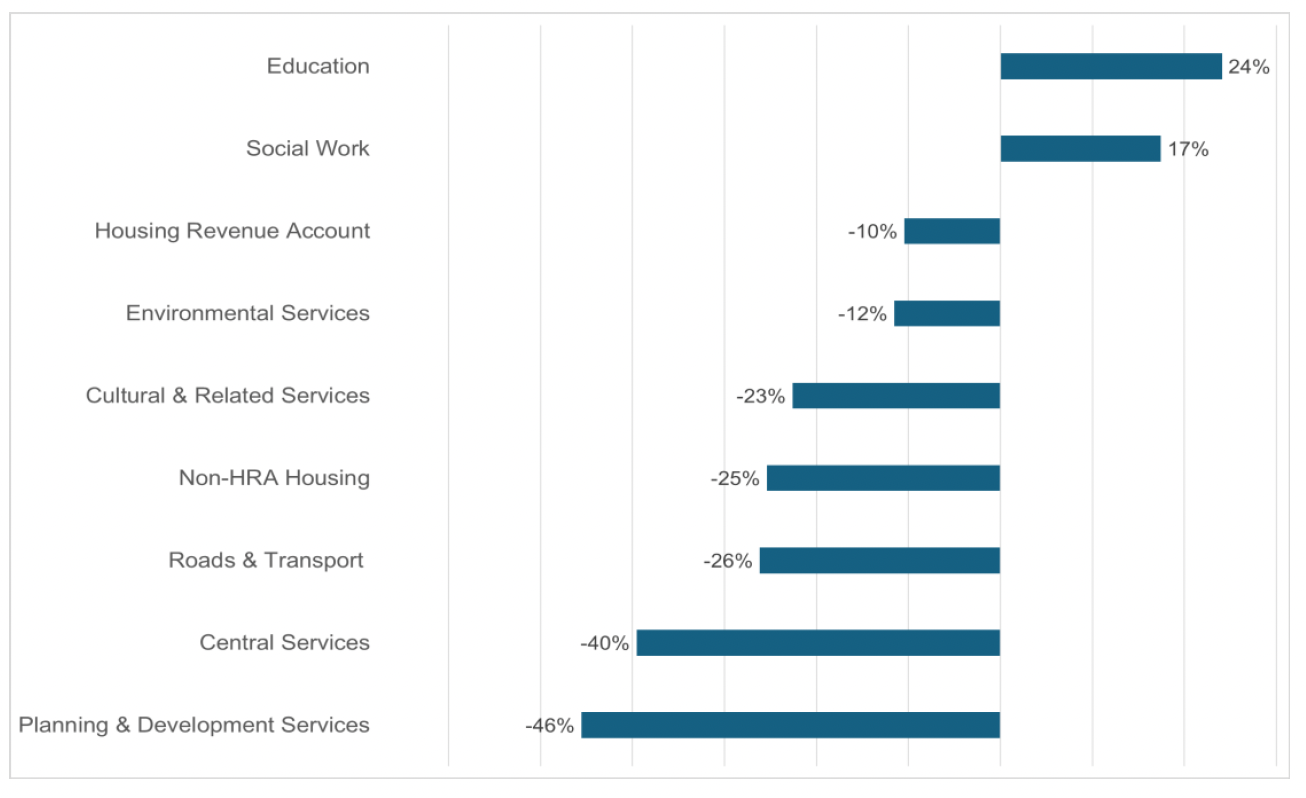
The table below shows the percentage change in real terms net revenue expenditure from 2013/14 to 2024/25. Only social work and education have seen real terms increases.
The variation in council spending on education will reflect a number of factors including composition of the elected members who ultimately approve budget decisions, and variations in the teacher staffing formula used across Scotland for schools (accounts for variations in number of DHTs for example in secondary schools of a similar size) and devolved school management schemes (some issues are devolved such as SQA budgets while others are held centrally).
Analysis from the Accounts Commission[89] did not find a link between spending per pupil and educational attainment. For example, councils with higher spending per primary pupil do not always have higher proportions of pupils achieving expected CfE levels in numeracy or literacy. Similarly, councils with higher spending per secondary pupil do not always have higher attainment at senior level, and some with lower spending per pupil have higher rates of attainment. Many factors impact on the average spend per pupil such as teacher demographics, local choices over non ring-fenced elements of the education staffing budget, public-private partnership/ public finance initiative (PPP/PFI) contract costs and arrangements, service design and management structure.
Statutory duties and staffing costs (around 70% of education spending) severely restrict how councils can allocate resources. Given the increase in teachers’ salaries and the freeze on teacher numbers, it significantly limits how much local councils spend on other services such as ASN, ELC, etc.
At the time of setting their 2025/26 budgets, councils identified a combined revenue budget gap of around £647 million. At a council level, budget gaps ranged from £70.3 million in the City of Edinburgh Council to £4.4 million in Eilean Siar. This represents five per cent and three per cent of their respective total revenue budgets.
Councils are anticipating that funding pressures will continue, citing several key assumptions that inform budgets in the medium term. Where the information was available:
- most councils report the pressures around annual pay settlements, with many expecting three per cent increases to 2027/28. This, alongside higher employer’s National Insurance contributions, increasing overall workforce costs
- potential increases to employer pension contributions, following recent reductions in these
- a majority of councils also reference general inflationary pressures, including increasing costs of goods and services, making councils’ operations more expensive
- several councils are also projecting flat cash funding settlements from the Scottish Government
- potential annual increases to council tax rates with a lack of consistency on the projected expected increase from individual councils.
Reporting
Local council finances in Scotland are reported formally on an annual basis, with key financial statistics and audits published yearly. Audit Scotland produces an annual Financial Bulletin on local government to provide an independent analysis of the financial performance of all 32 councils.
The Accounts Commission has a statutory duty to direct councils to publish information enabling comparisons of performance between councils. Over time this will show how well councils are improving local outcomes in partnership with other public bodies. This helps councils improve services, giving local people a better understanding of the performance of their council. This also encourages the use of the Local Government Benchmarking Framework.
The Accounts Commission have indicated the need for budget papers to present key information in a way that is easily accessible and understandable to the public. Even some local appointed auditors reported difficulty in easily identifying key aspects of councils’ budgets (e.g., the scale of budget gaps, likely impacts of budget reductions and/or how any planned savings to balance budgets were to be achieved). This raises important questions about how effectively council budget papers communicate to local elected members and local communities what the impact of different budget choices might mean and the overall financial health of their local council. It has long been recognised that there is scope to improve the understandability of council accounts to the public. [90]
The Accounts Commission last published a comprehensive report on how efficiently and effectively local councils are using their resources to maximise pupils’ achievement in schools in 2014. Their latest report, published in 2021[91], explored how effectively local councils are closing the poverty related attainment gap.